“One leg lets you down” — what the offer really promises
I have a friend who treats acca insurance as a personality trait. Every weekend, he tells me he’s “fine, mate, I’ve got insurance on the six-fold”. He proceeds to lose the slip when two legs go down, then sulks until Tuesday because he didn’t read the terms. Acca insurance has saved him exactly twice in three years.
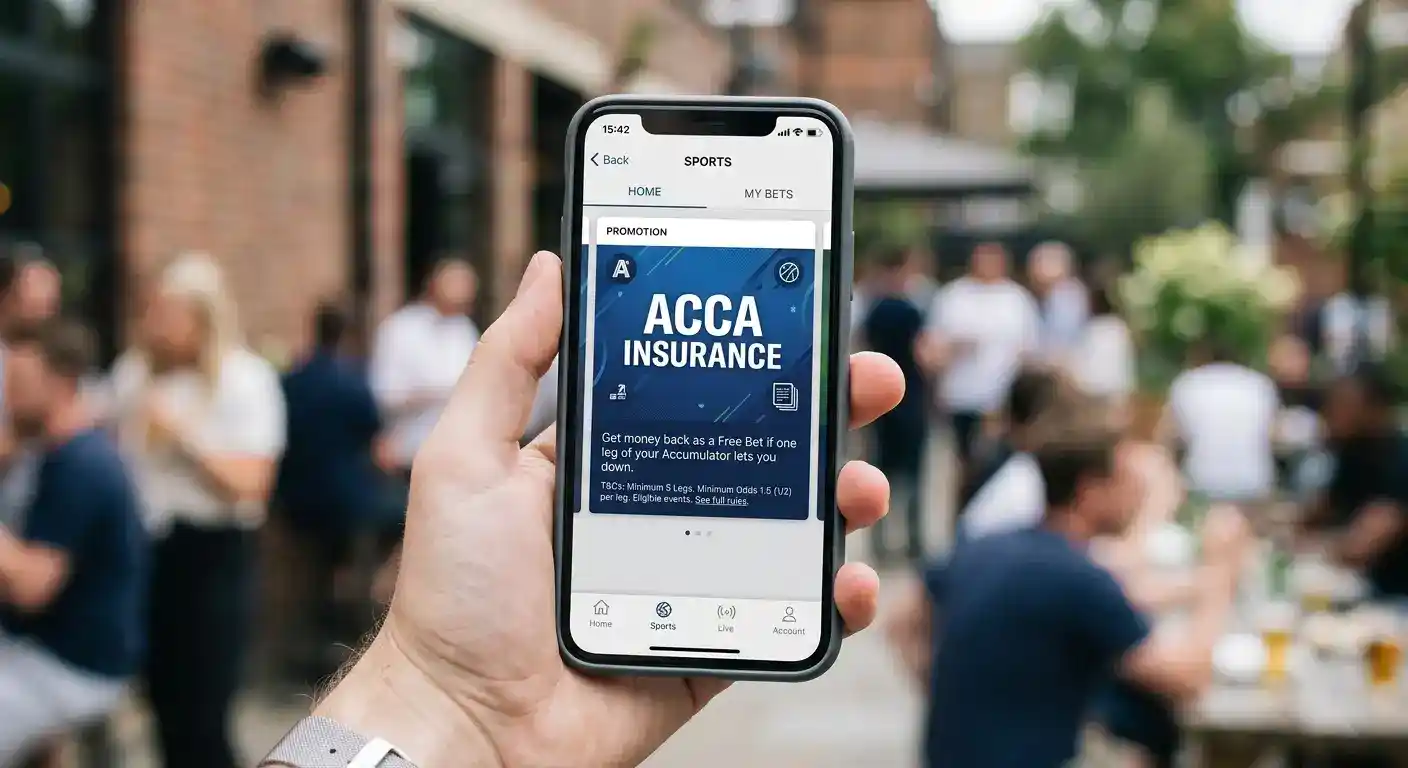
The phrase is loud and the product is genuine. UK operators advertise it across every football weekend because it works as a hook — the punter sees the word “insurance” and feels protected. The structure of the offer is much narrower than the marketing implies, and the difference between feeling protected and being protected is where most of the money quietly flows back to the bookmaker.
Mechanics — when the refund kicks in
The mechanic is binary. If exactly one leg of your qualifying acca loses while every other leg wins, the operator refunds your stake. If two legs lose, no refund. If your acca wins outright, no refund — you got paid the proper way. Acca insurance is, in mathematical language, an “only one leg failing” call option on your slip.
That binary trigger is the first thing punters misread. You don’t get partial coverage. You don’t get half your stake back if two legs fail. The promise is specifically “one leg lets you down” and the boundary holds at exactly one. The probability of triggering insurance is also smaller than instinct suggests. On a five-fold of selections each priced around 1.80, the probability that exactly one leg loses while four win is roughly 22% — meaningful, but not the “I’m probably covered” feeling the marketing implies.
The refund itself is also delayed. Most operators settle insurance refunds within 24 hours of the final qualifying match completing, not at the moment the losing leg goes down. You can’t react in-play to having “insurance kicked in” because the refund doesn’t materialise until the rest of the slip resolves.
Free bet token versus cash — the value gap
This is where most of the actual value disappears. The form the refund takes — cash or free bet — changes the expected value of the offer by 25% or more.
A cash refund of £25 is worth £25. You can withdraw it, you can stake it on anything, and there are no conditions attached. A free bet token of £25 is worth something less than £25. The standard industry shorthand puts a £25 free bet at roughly £18 to £20 of effective cash value, depending on the minimum odds and the stake-not-returned mechanic. The reason is that the free-bet stake is not returned on a winning bet — only the winnings — so you need to back something at decent odds to recover the underlying value.
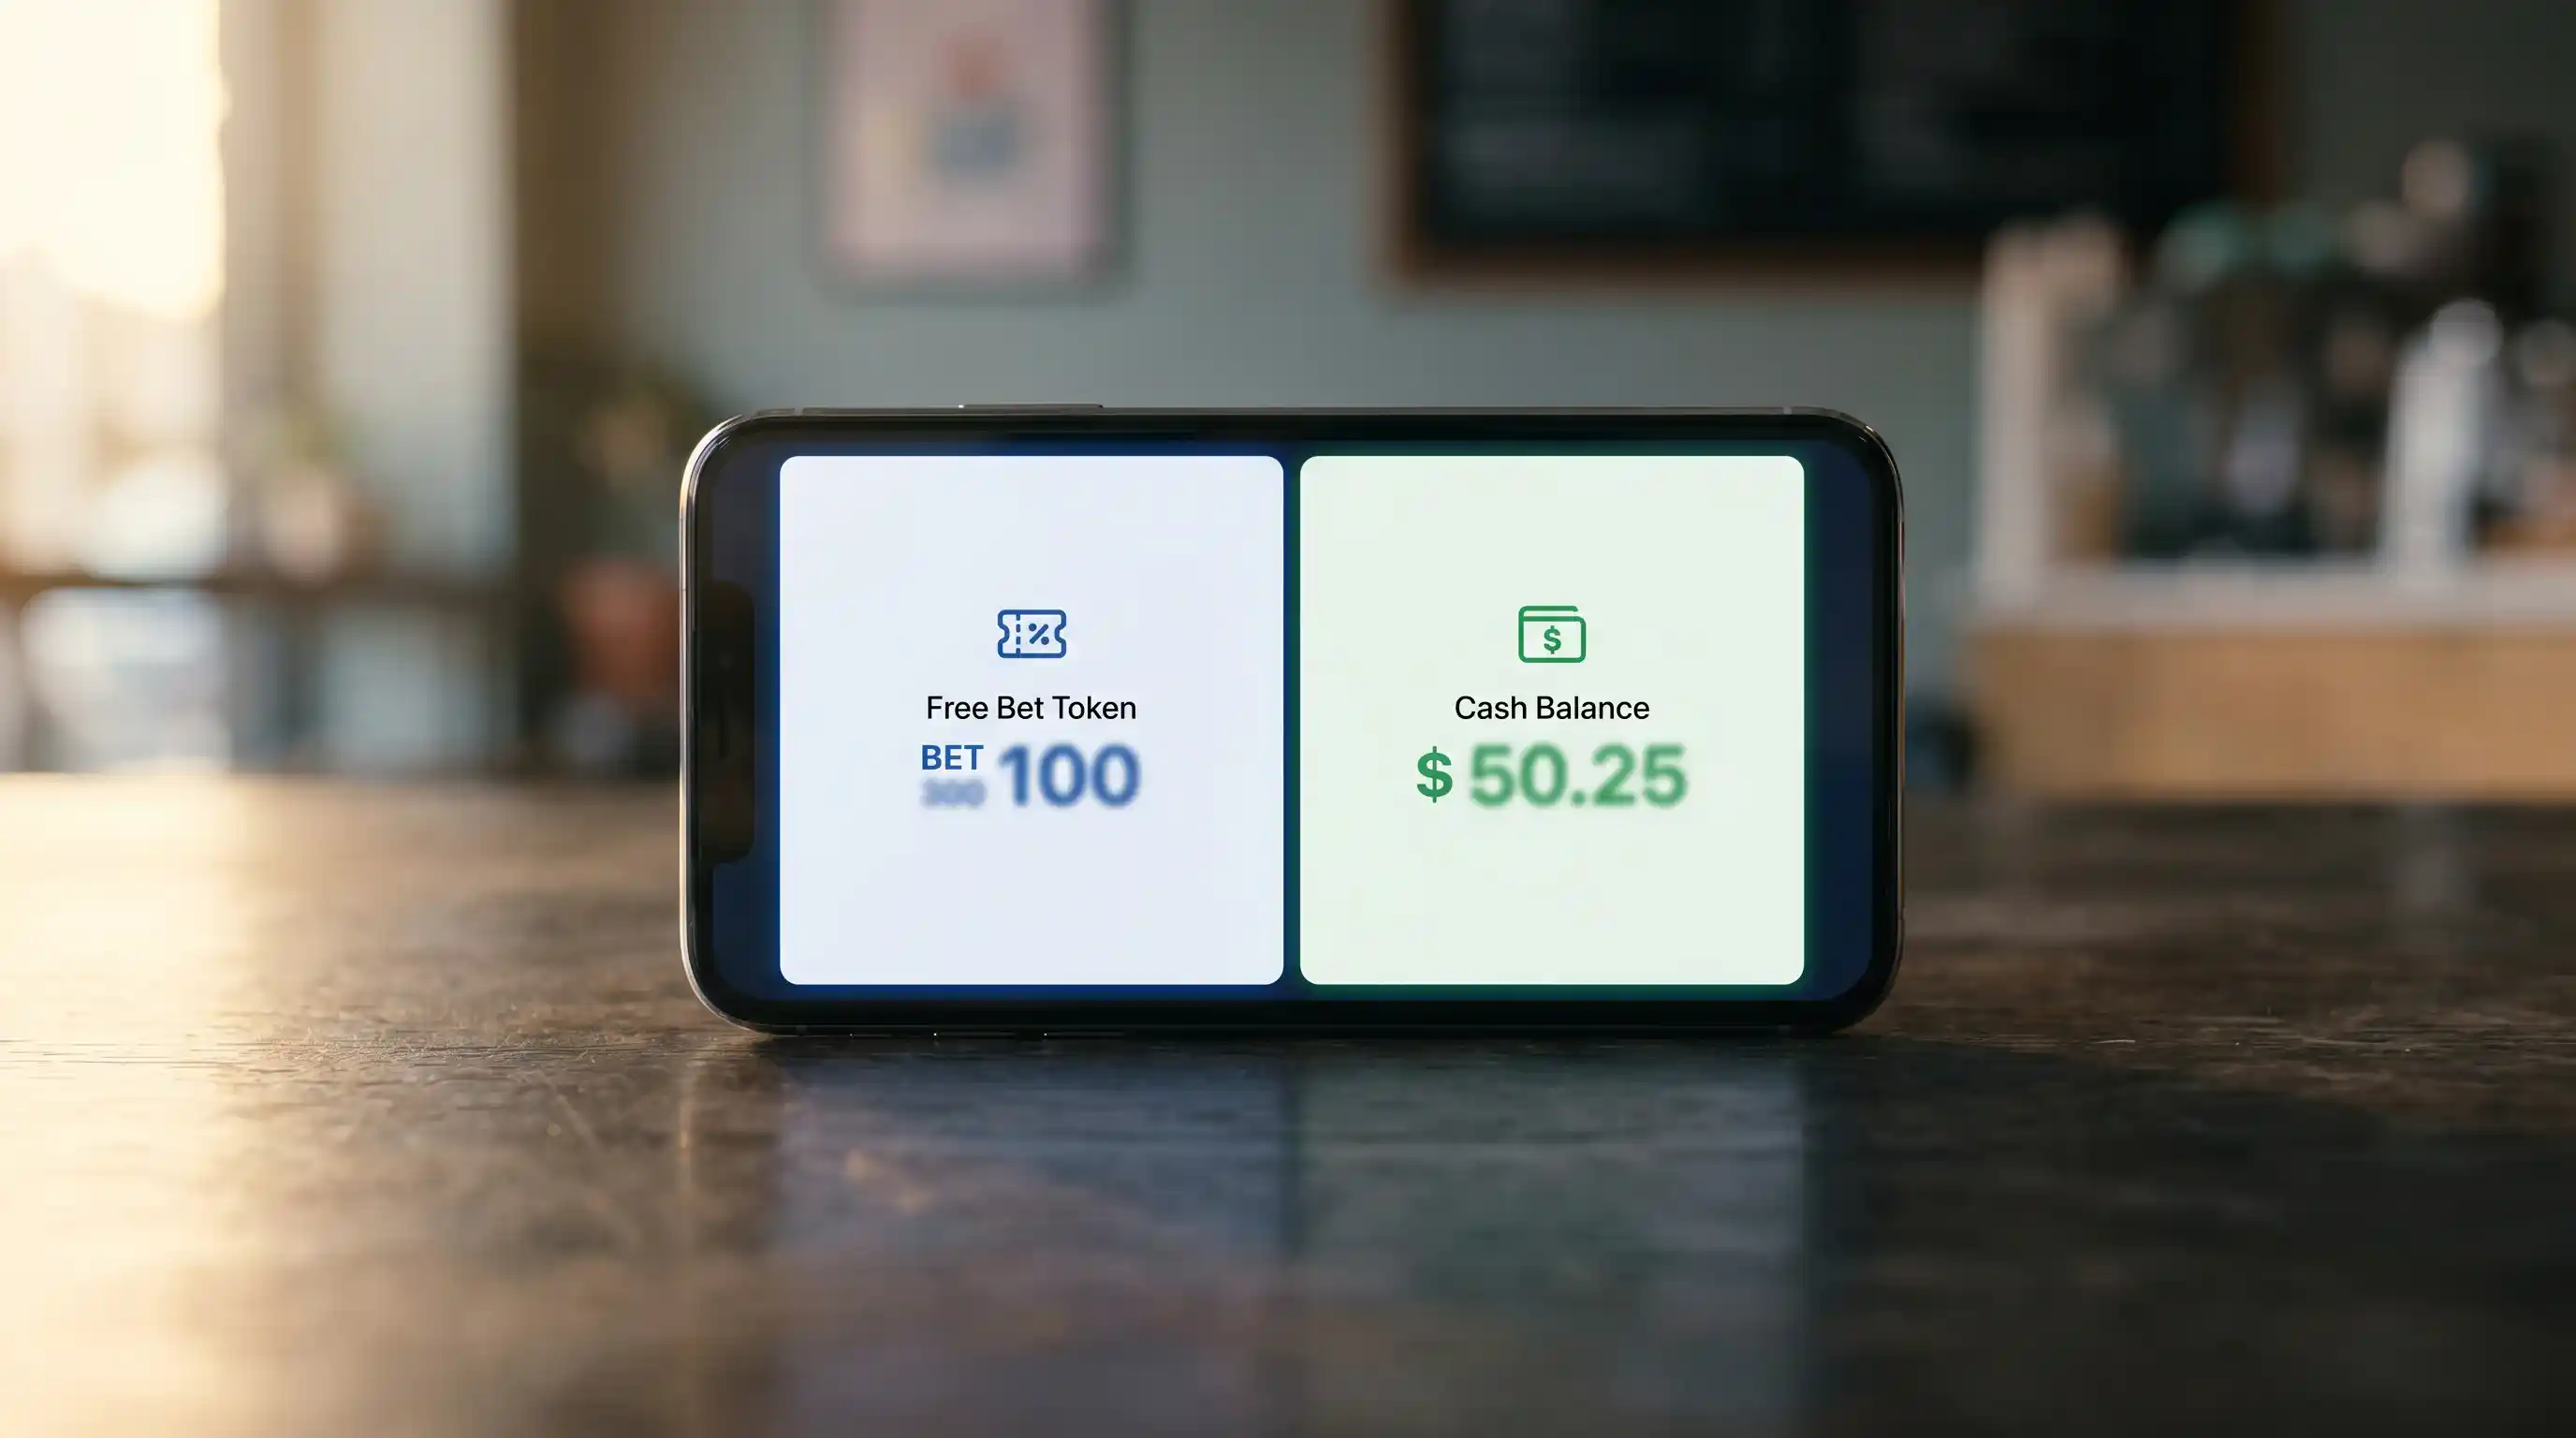
UK operators are roughly split. Some legacy high-street brands offer cash refunds on acca insurance because that’s how they’ve always run the promotion. Others — particularly newer mobile-first brands — default to free-bet tokens, which carry the appearance of cash without the substance. The total UK regulated betting market saw 24.4 million active accounts at the end of FY2024–25, with 34 million new registrations over the year, and a meaningful share of those registrations were drawn by exactly this kind of promotional language. Operators know what the word “insurance” does to acquisition cost. They also know what a free-bet token saves them on the back end.
Always read the offer terms before placing the slip. If the answer to “is the refund cash or token?” isn’t immediately obvious from the offer page, assume token.
Minimum legs, minimum odds and excluded markets
The qualifying conditions are where the offer narrows considerably from the headline. Most UK operators require a minimum of four legs to qualify — some require five. Below that, the slip isn’t an acca for insurance purposes regardless of how the operator otherwise classifies it.
Minimum odds per leg are universal. The standard floor sits at 1.40 (2/5), meaning even-money home wins don’t count. The slip’s total odds also typically need to clear a threshold — often 6/1 or 7/1 minimum — to filter out anchor-heavy slips that would otherwise trigger insurance too cheaply.
Market exclusions catch punters out more than the odds floors. Most UK acca insurance offers exclude correct score, scorecast, first goalscorer, and any same-game multi (Bet Builder) legs. The promotion is built around standard 1X2 and certain Over/Under and BTTS markets. If you’ve added a 4-0 correct score to your slip thinking it’s a clever leg, you’ve also quietly disqualified the whole acca from insurance.
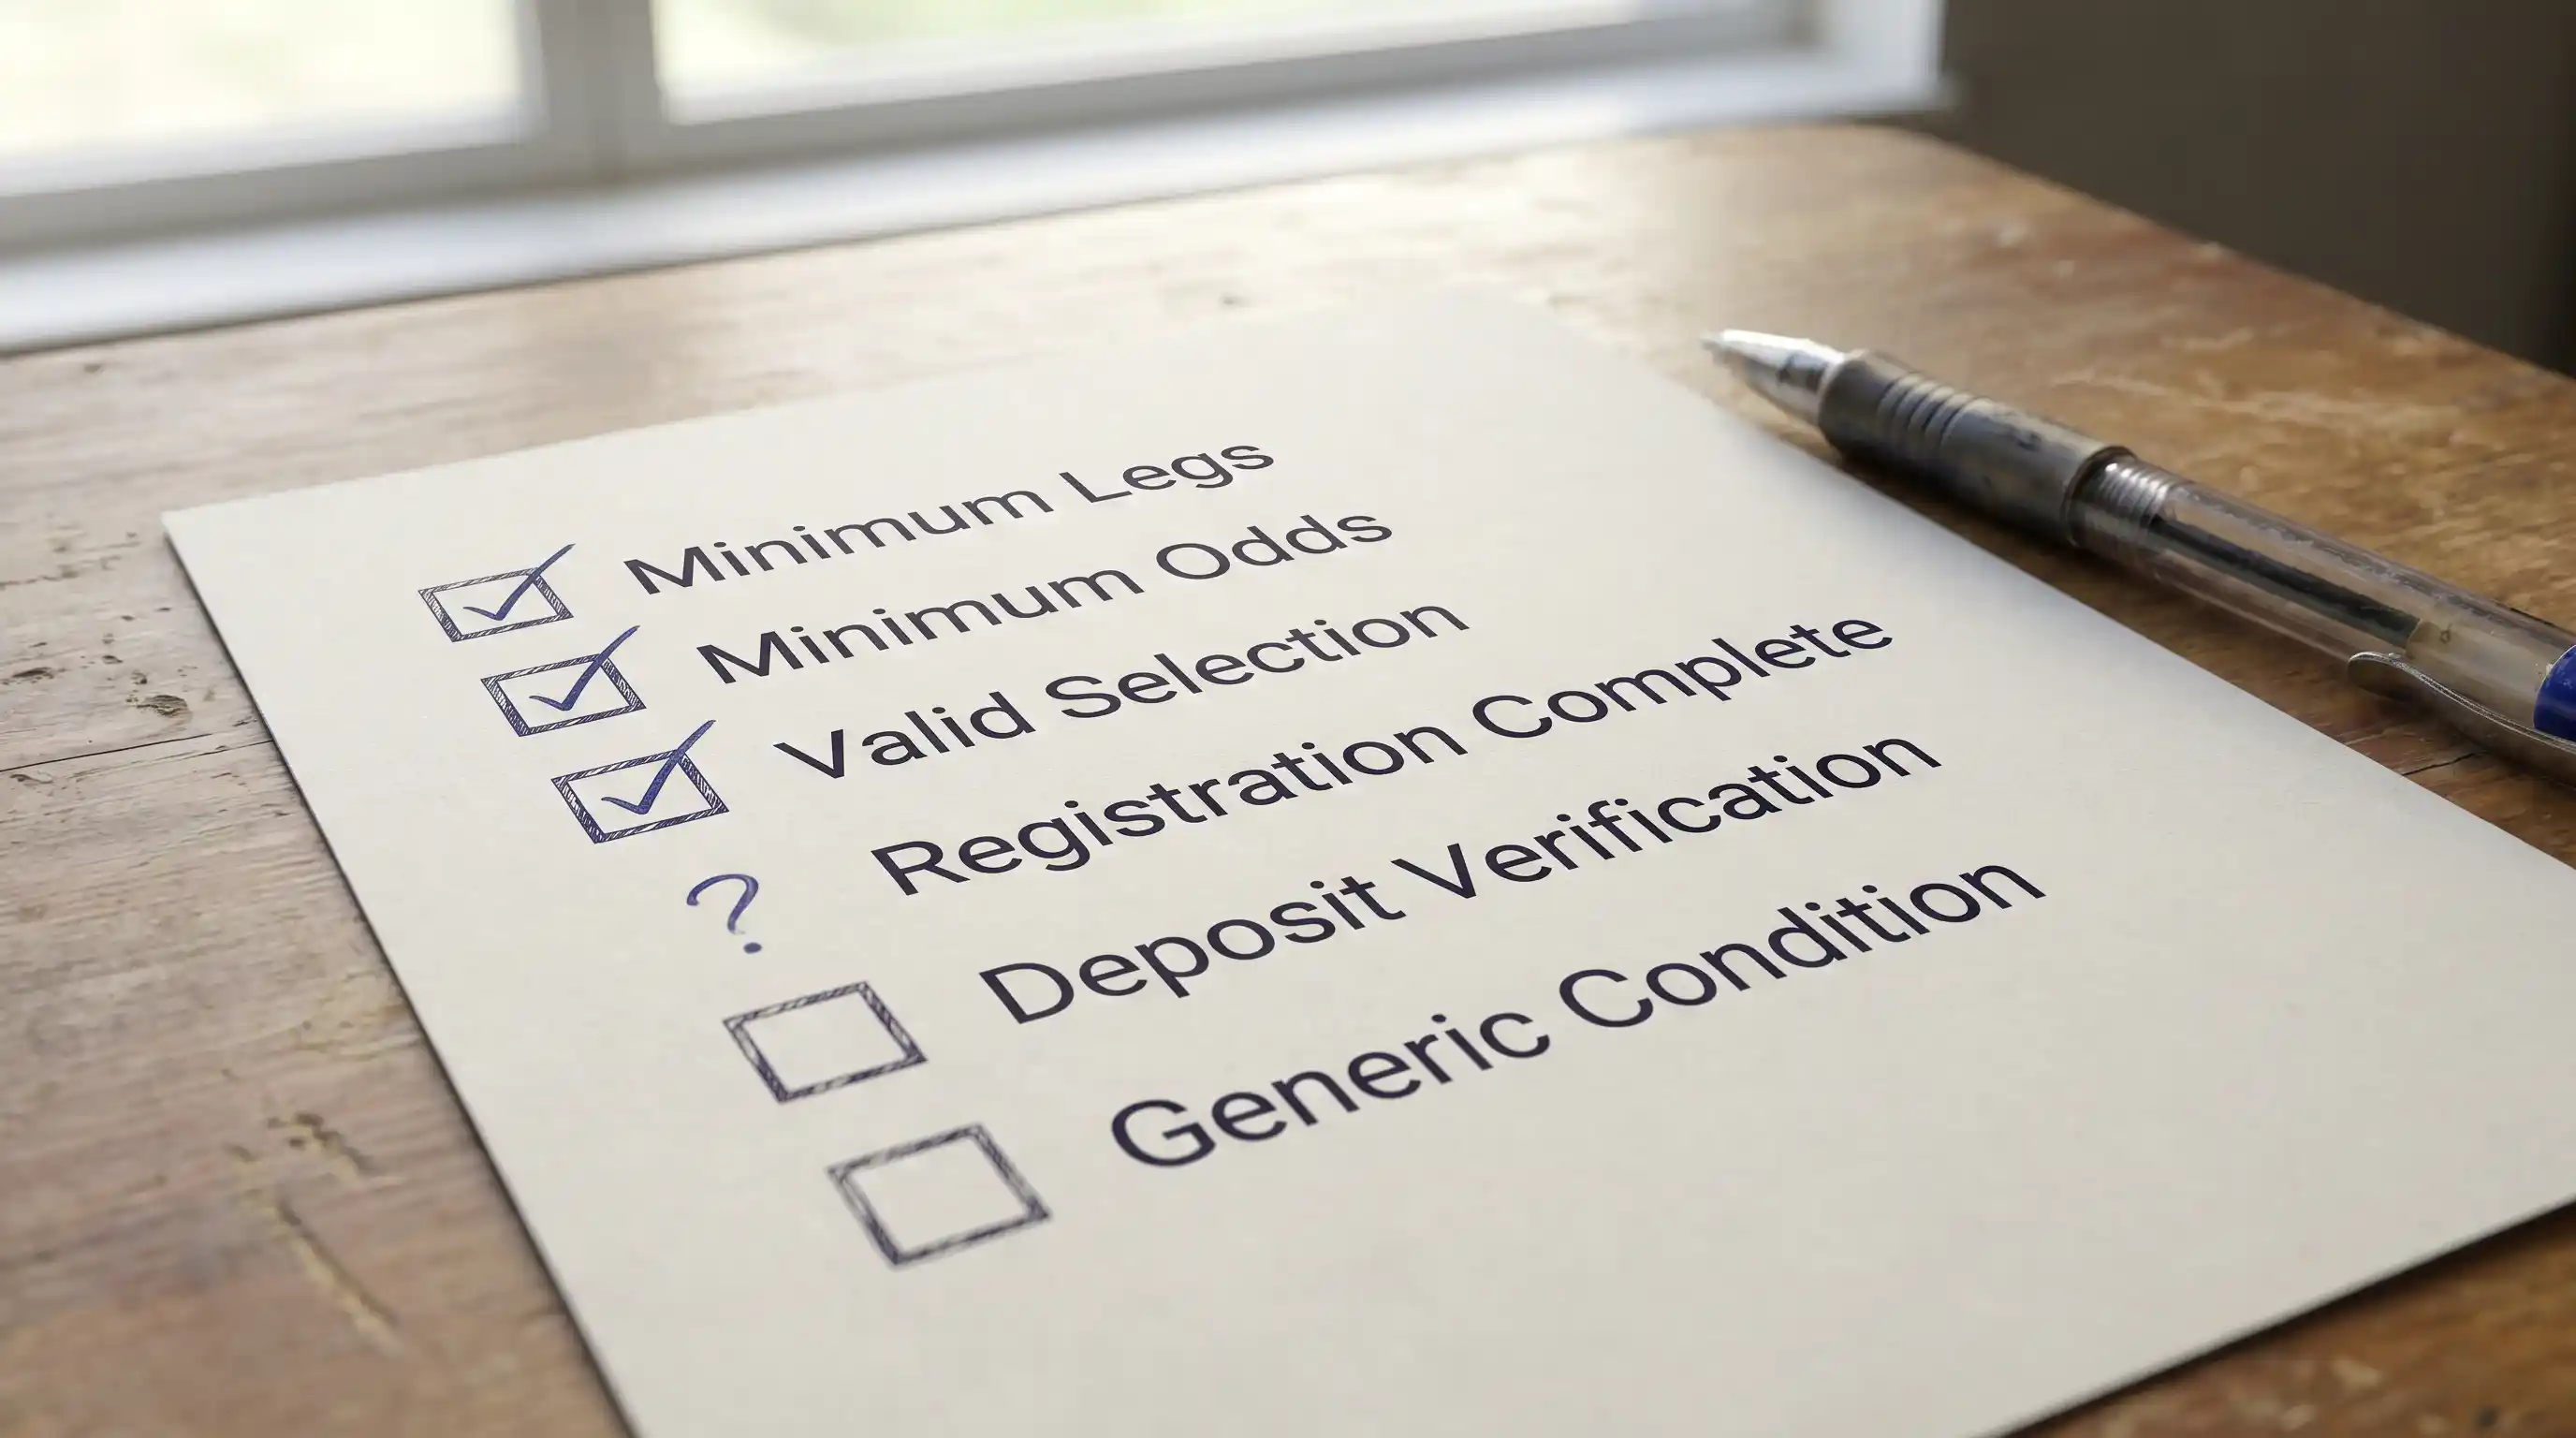
Maximum-stake caps complete the picture. Refunds are typically capped at £25 — sometimes £20, occasionally £50. Stakes above the cap revert to standard settlement. A £50 acca with a £25 insurance cap is, in effect, a £25 insured bet plus a £25 uninsured bet stitched together.
Operator variations across the UK market
Within those broad rules, operators differ enough that the same nominal “acca insurance” offer can be worth twice as much at one operator as at another. The variables that matter are the refund format (cash versus free bet), the minimum legs (four versus five), the qualifying-odds floor (1.40 versus 1.60), the maximum refund cap (£20 versus £50), and the market eligibility (1X2-only versus broader).
I’d look at the offer’s terms in roughly that order. The cash-versus-token call alone changes EV by 20–30%. The minimum-legs call shifts the offer between four-fold and five-fold territory. The maximum cap determines whether you can stake the offer meaningfully or are forced down to insurance-only sizing.
One quiet pattern I’ve noticed — operators that run cash refunds tend to be tighter on the other variables (higher minimum legs, tighter market eligibility, lower caps). Operators that run free-bet refunds tend to be looser on the surface (four legs minimum, broader market list, higher caps) because the underlying refund is worth less anyway. The marketing prominence of the offer is inversely related to its actual value.
Does acca insurance actually shift expected value?
The honest answer is that it shifts EV by a small positive amount and the magnitude depends heavily on the specific terms.
Take a five-fold where each leg is priced at 2.00 (50% probability per leg). Probability that the whole acca wins: 3.125%. Probability that exactly one leg fails: 15.6%. Probability that two or more legs fail: 81.25%.
Standard expected value on a £10 stake at total odds of 32.00: £10 × 3.125% × 32 = £10. Even-money in EV terms because we used fair prices. In reality the legs are priced with overround, so the unadjusted EV is below stake.
Now add cash acca insurance with a £25 cap. The probability of triggering insurance is 15.6%, the refund is £10 (capped above stake), so the additional EV is £10 × 15.6% = £1.56. That’s a 15.6% uplift to the standard EV of the slip — meaningful enough to be worth caring about.
Same calculation with a free-bet refund worth approximately £7 in cash terms: additional EV is £7 × 15.6% = £1.09. Still positive, but the uplift drops to under 11%. Tighten the minimum legs to five-only, exclude Bet Builder markets, cap at £20 — and the EV uplift can fall below 8%.
None of those numbers turn a losing acca product into a winning one. Compounded overround across five Premier League selections is well above 20%, and a free-bet refund of 8% in EV doesn’t close that gap. Acca insurance makes a bad product slightly less bad. For broader structural advice on building accas that survive the variance in the first place, my guide to football accumulator strategy covers the leg-structure and bankroll questions that matter more than any insurance offer.
The protection that protects the operator too
Acca insurance is a real product with real expected-value uplift. It’s also a brilliant piece of acquisition marketing — the word “insurance” lands emotionally in a way that “small probabilistic refund on a narrow set of qualifying conditions” never would.
The honest framing is that acca insurance is a modest bonus stapled onto a high-margin product. If you were already going to place a five-fold and the insurance is cash-funded with no nasty exclusions, take the offer. It improves your slip by a few percent of EV. If you find yourself building accas you wouldn’t otherwise place because “the insurance covers it”, you’ve fallen for the marketing rather than the maths. The slip is still uninsured against the most common failure mode — multiple legs losing — and you’ve added structural risk to your week for the comfort of a refund that probably won’t trigger.
Can I cash out and still claim acca insurance?
No. Cashing out closes the bet at the agreed price and removes the original acca from the operator"s settlement queue. Acca insurance only applies to the original slip running to its natural conclusion with exactly one losing leg, so the cash-out action voids any insurance eligibility.
Does acca insurance count on a Bet Builder leg?
Almost never. Bet Builder (same-game multi) selections are explicitly excluded from acca insurance terms at the major UK operators. The insurance product was designed for distinct, uncorrelated match selections and the operator won"t apply it to a slip containing same-game correlated legs.
Why is the refund capped at £25 on most UK sites?
The cap controls the operator"s downside exposure on the offer. £25 is the historical retail standard — large enough to be meaningful as a hook but small enough that a few thousand triggered insurance refunds per weekend don"t blow up the promotional budget. A handful of operators run £50 caps as a competitive differentiator.
This material was created by the Pitchledger team.
