The bankroll I blew up in three weekends and the lesson it cost
Years ago, early in my analytical career, I had a £500 bankroll for football betting. I had three good weekends in a row and convinced myself I’d cracked it. Stakes went from £20 per bet to £100 per bet. Fourth weekend, I had a normal stretch — five losses out of seven — and watched £400 evaporate in 90 minutes of Premier League football. The bankroll wasn’t gone but the confidence was.
That experience taught me what every analytical punter learns the hard way: the mathematics of value betting is sound, but the mathematics of variance is unforgiving. A 55% hit rate bettor will have stretches of 10 losses in 15 bets purely from random variance. If your stake sizing assumes you’ll hit at expected rate every weekend, those stretches blow up your bankroll. Bankroll management isn’t optional supplementary discipline — it’s the load-bearing structure that lets value betting work at all.
The size of bankroll you actually need
The first question most punters get wrong is how much capital they need to bet football seriously. The answer depends on average edge size, stake-as-percentage-of-bankroll, and variance tolerance. For a punter targeting 3-5% expected ROI on positive-EV bets with 2% Kelly-fractional staking, the minimum sustainable bankroll is around 100 average bet sizes.
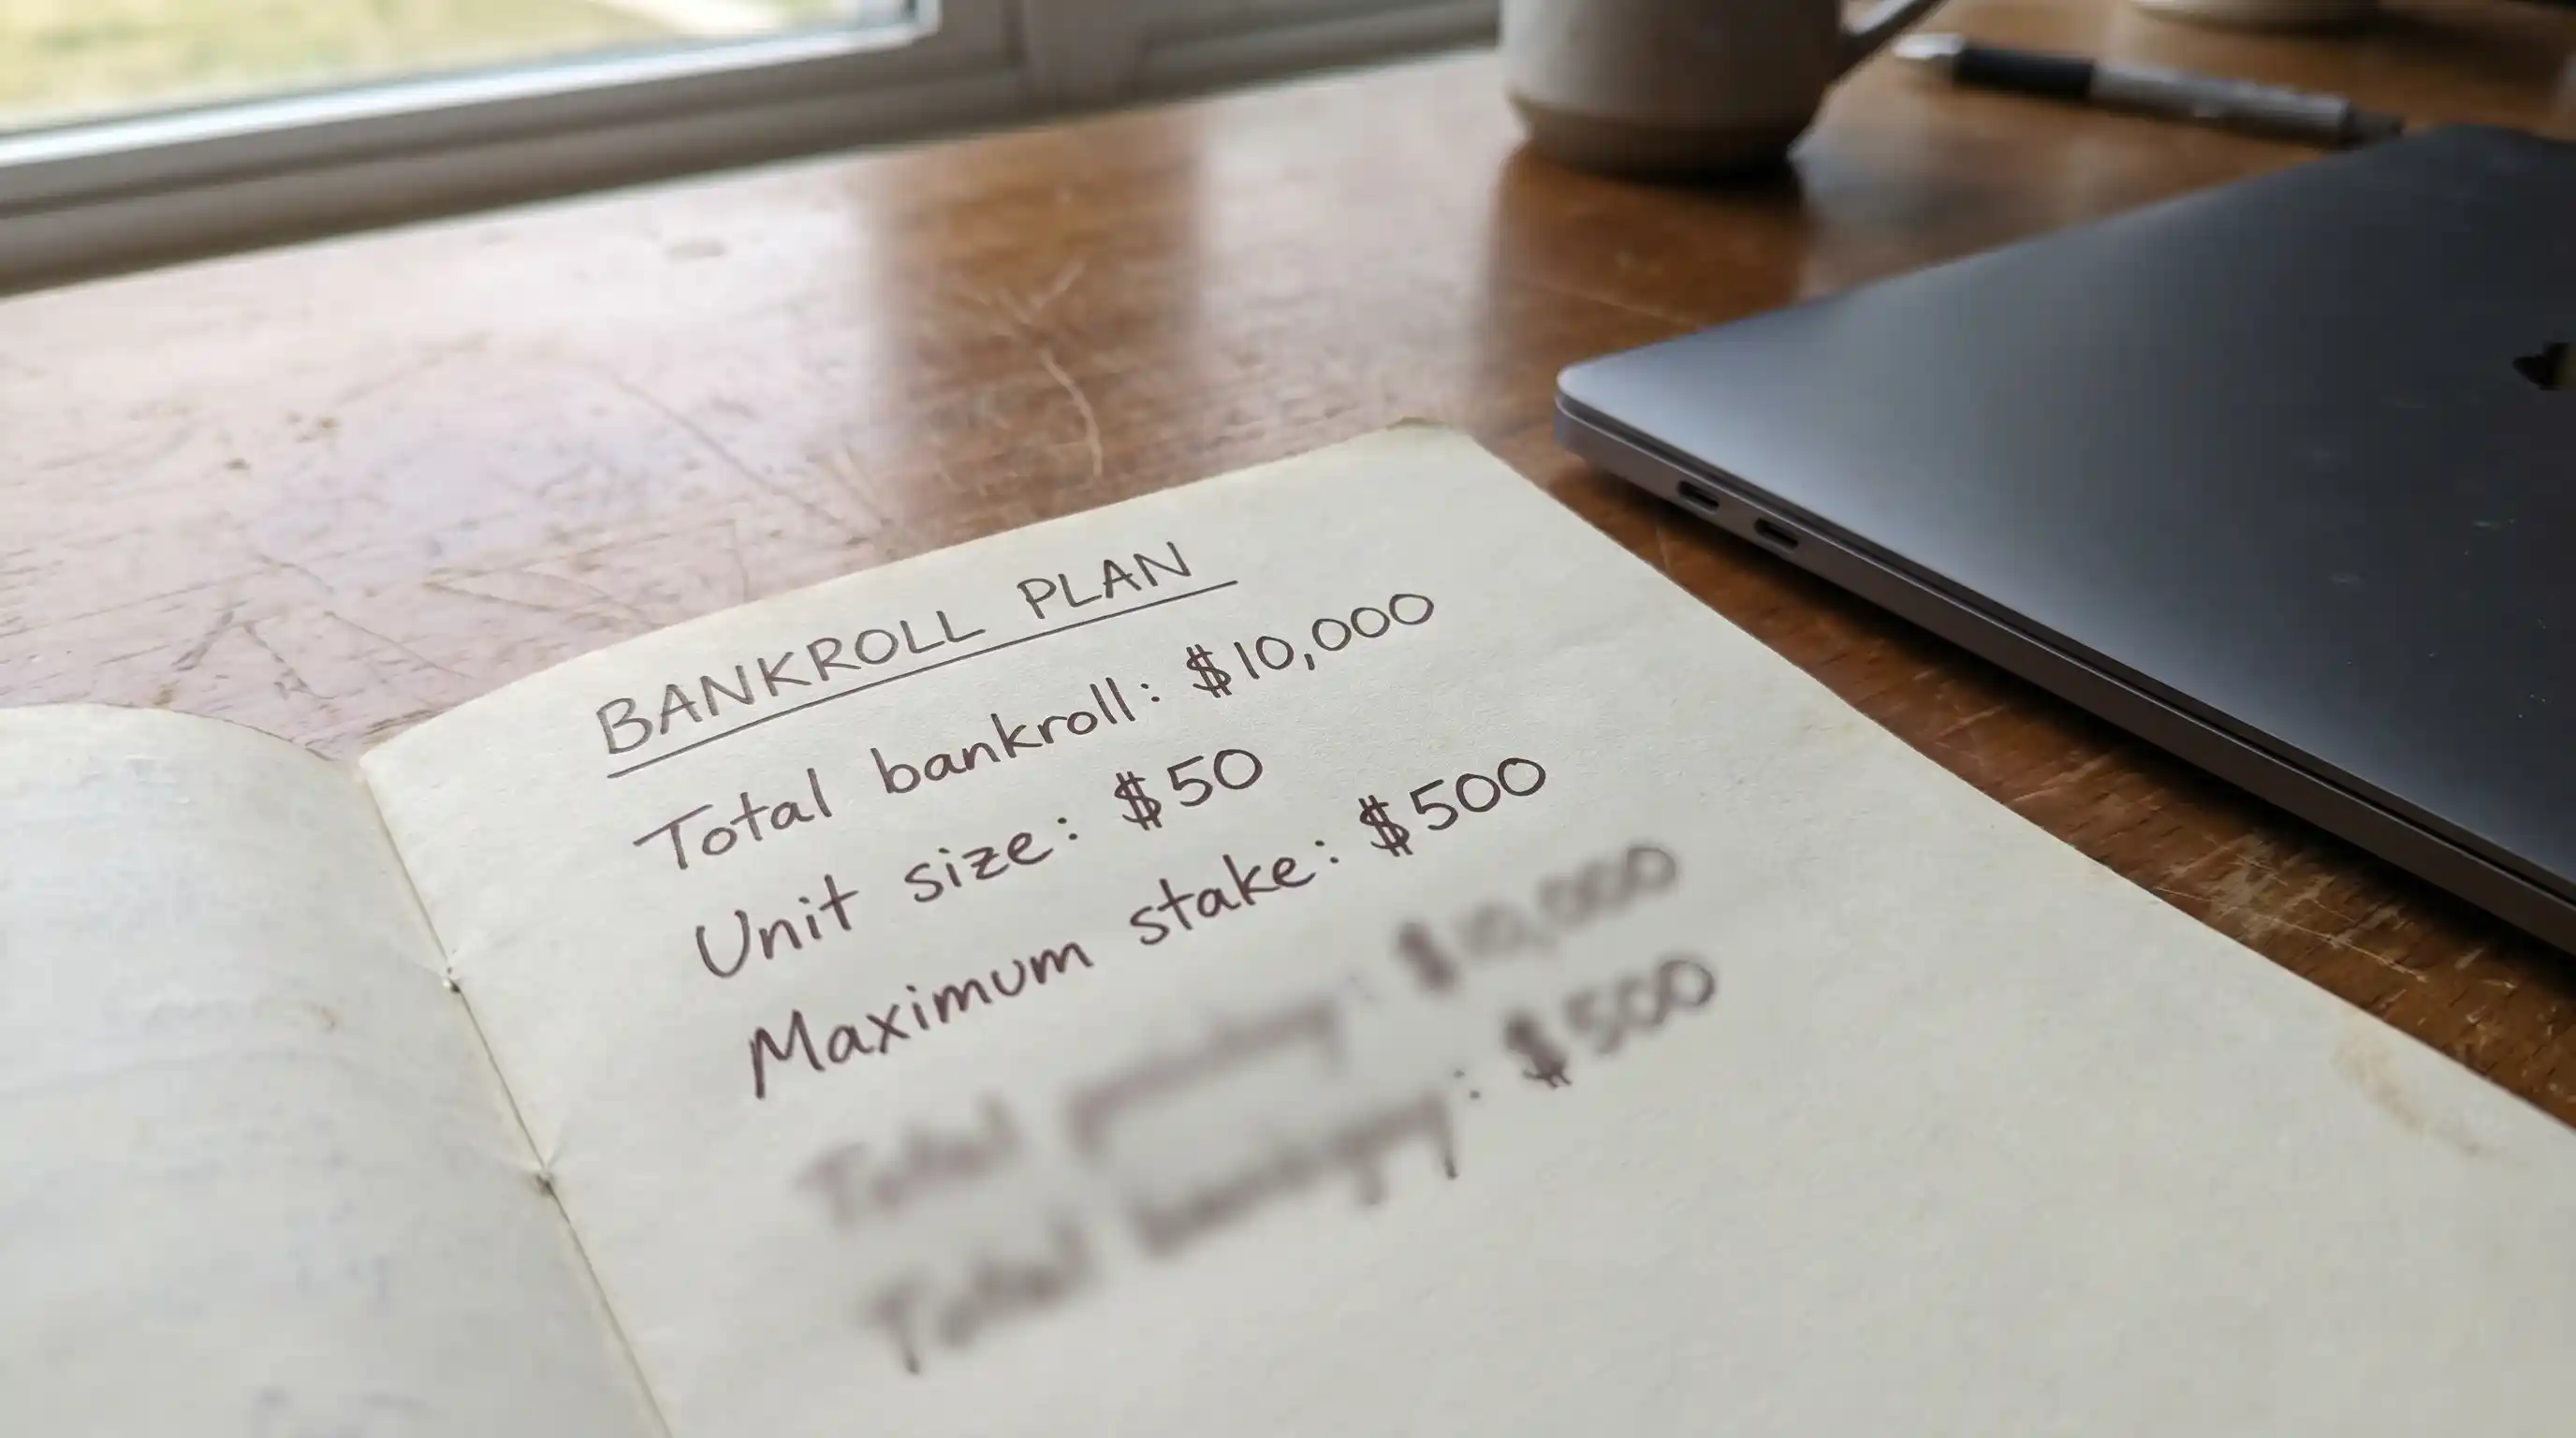
That sounds large. Most retail punters bet at 5-10% of their bankroll per wager and run out of capital after their first significant losing streak. The discipline of betting small percentages — 1% to 3% per wager — produces longer-lived bankrolls and more robust profit accumulation. The price of that discipline is the willingness to feel that you’re under-staking on bets you feel confident about.
UK gambling reported £1.3bn in football GGY last year against 24.4M active accounts. The arithmetic of average loss per account points to retail accounts losing modest amounts annually — but the modal punter loses, the small minority who profit do so by betting carefully against the modal pattern. Bankroll management is what separates those two groups more than any single tactical decision.
Flat staking versus proportional staking
Flat staking — betting the same amount every time — is the simplest approach and the right one for beginners. It removes stake-sizing as a variable, lets you focus on selection quality, and produces predictable variance that’s easy to monitor.
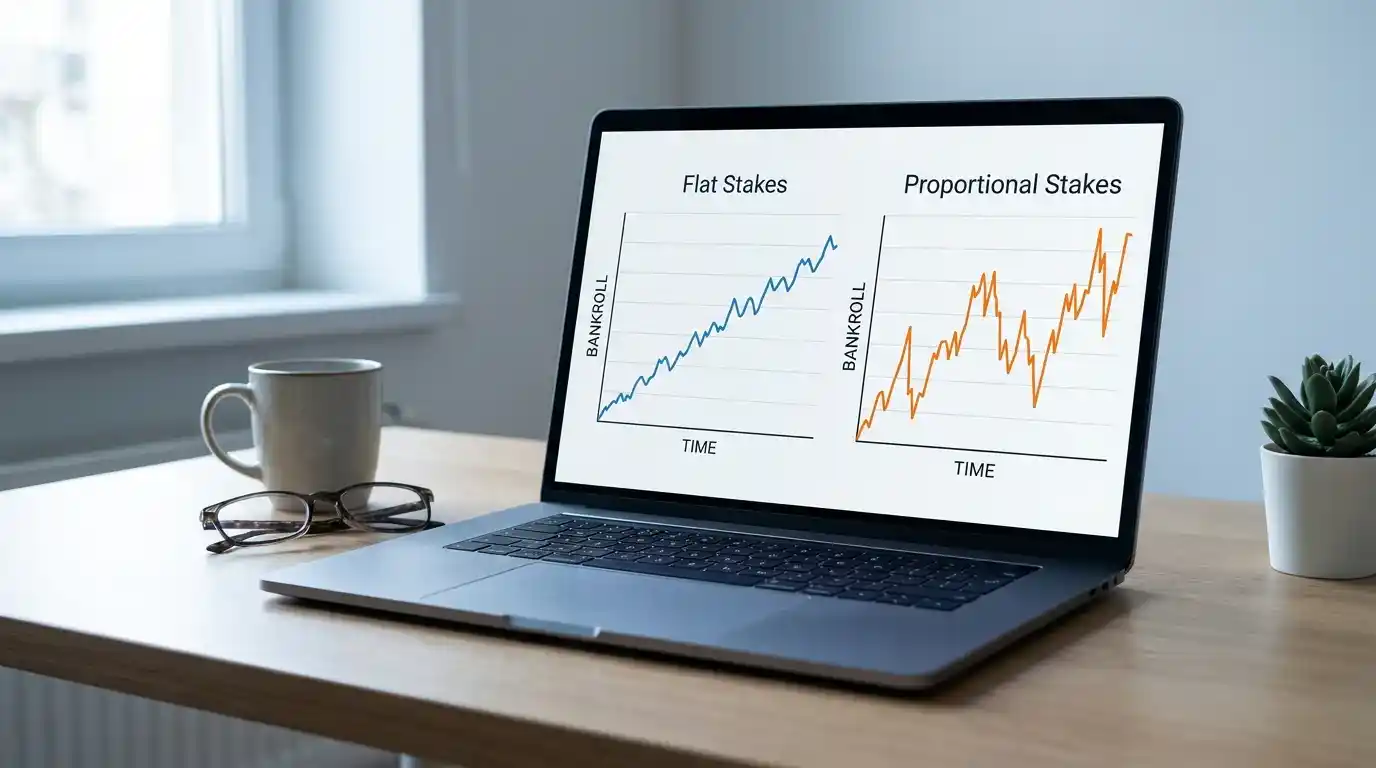
Proportional staking — betting more on higher-confidence wagers and less on lower-confidence wagers — produces faster long-run growth at the cost of higher variance. The Kelly criterion provides the mathematical optimum, but full Kelly is uncomfortable to bet through in real time. Most disciplined punters use fractional Kelly: half or quarter Kelly, which captures most of the growth benefit while reducing the variance.
The transition from flat to proportional should happen only after a bettor has built a CLV history demonstrating consistent edge across a few hundred bets. Before that history exists, proportional staking is unstable — you’re scaling stake size based on confidence estimates that haven’t been validated. After the history exists, proportional staking is a substantial growth accelerator.
Drawdown tolerance and emotional capital
Beyond the mathematical bankroll consideration is the emotional bankroll consideration. A statistically sustainable losing streak might be 8-12 consecutive losses, producing a 20-30% bankroll drawdown for a moderate-stake bettor. The mathematics says ride it out. The emotion says cut the losses, double the stakes, change the strategy.
That emotional pressure is what destroys most analytical betting strategies. The strategy doesn’t fail because the maths is wrong — it fails because the punter intervenes during a normal variance event. Bankroll management isn’t just about stake-sizing arithmetic; it’s about constructing a system that you can stick with through the inevitable variance.
A useful heuristic: choose stake sizes such that a 30% drawdown wouldn’t significantly distress you. If 30% of your bankroll evaporating over six weekends would shake your confidence in the strategy, your stakes are too high regardless of what the Kelly maths says. Drop them. Stake sizing has to clear both the mathematical and emotional thresholds, and the emotional threshold is usually the binding constraint.
The unit system and disciplined record-keeping
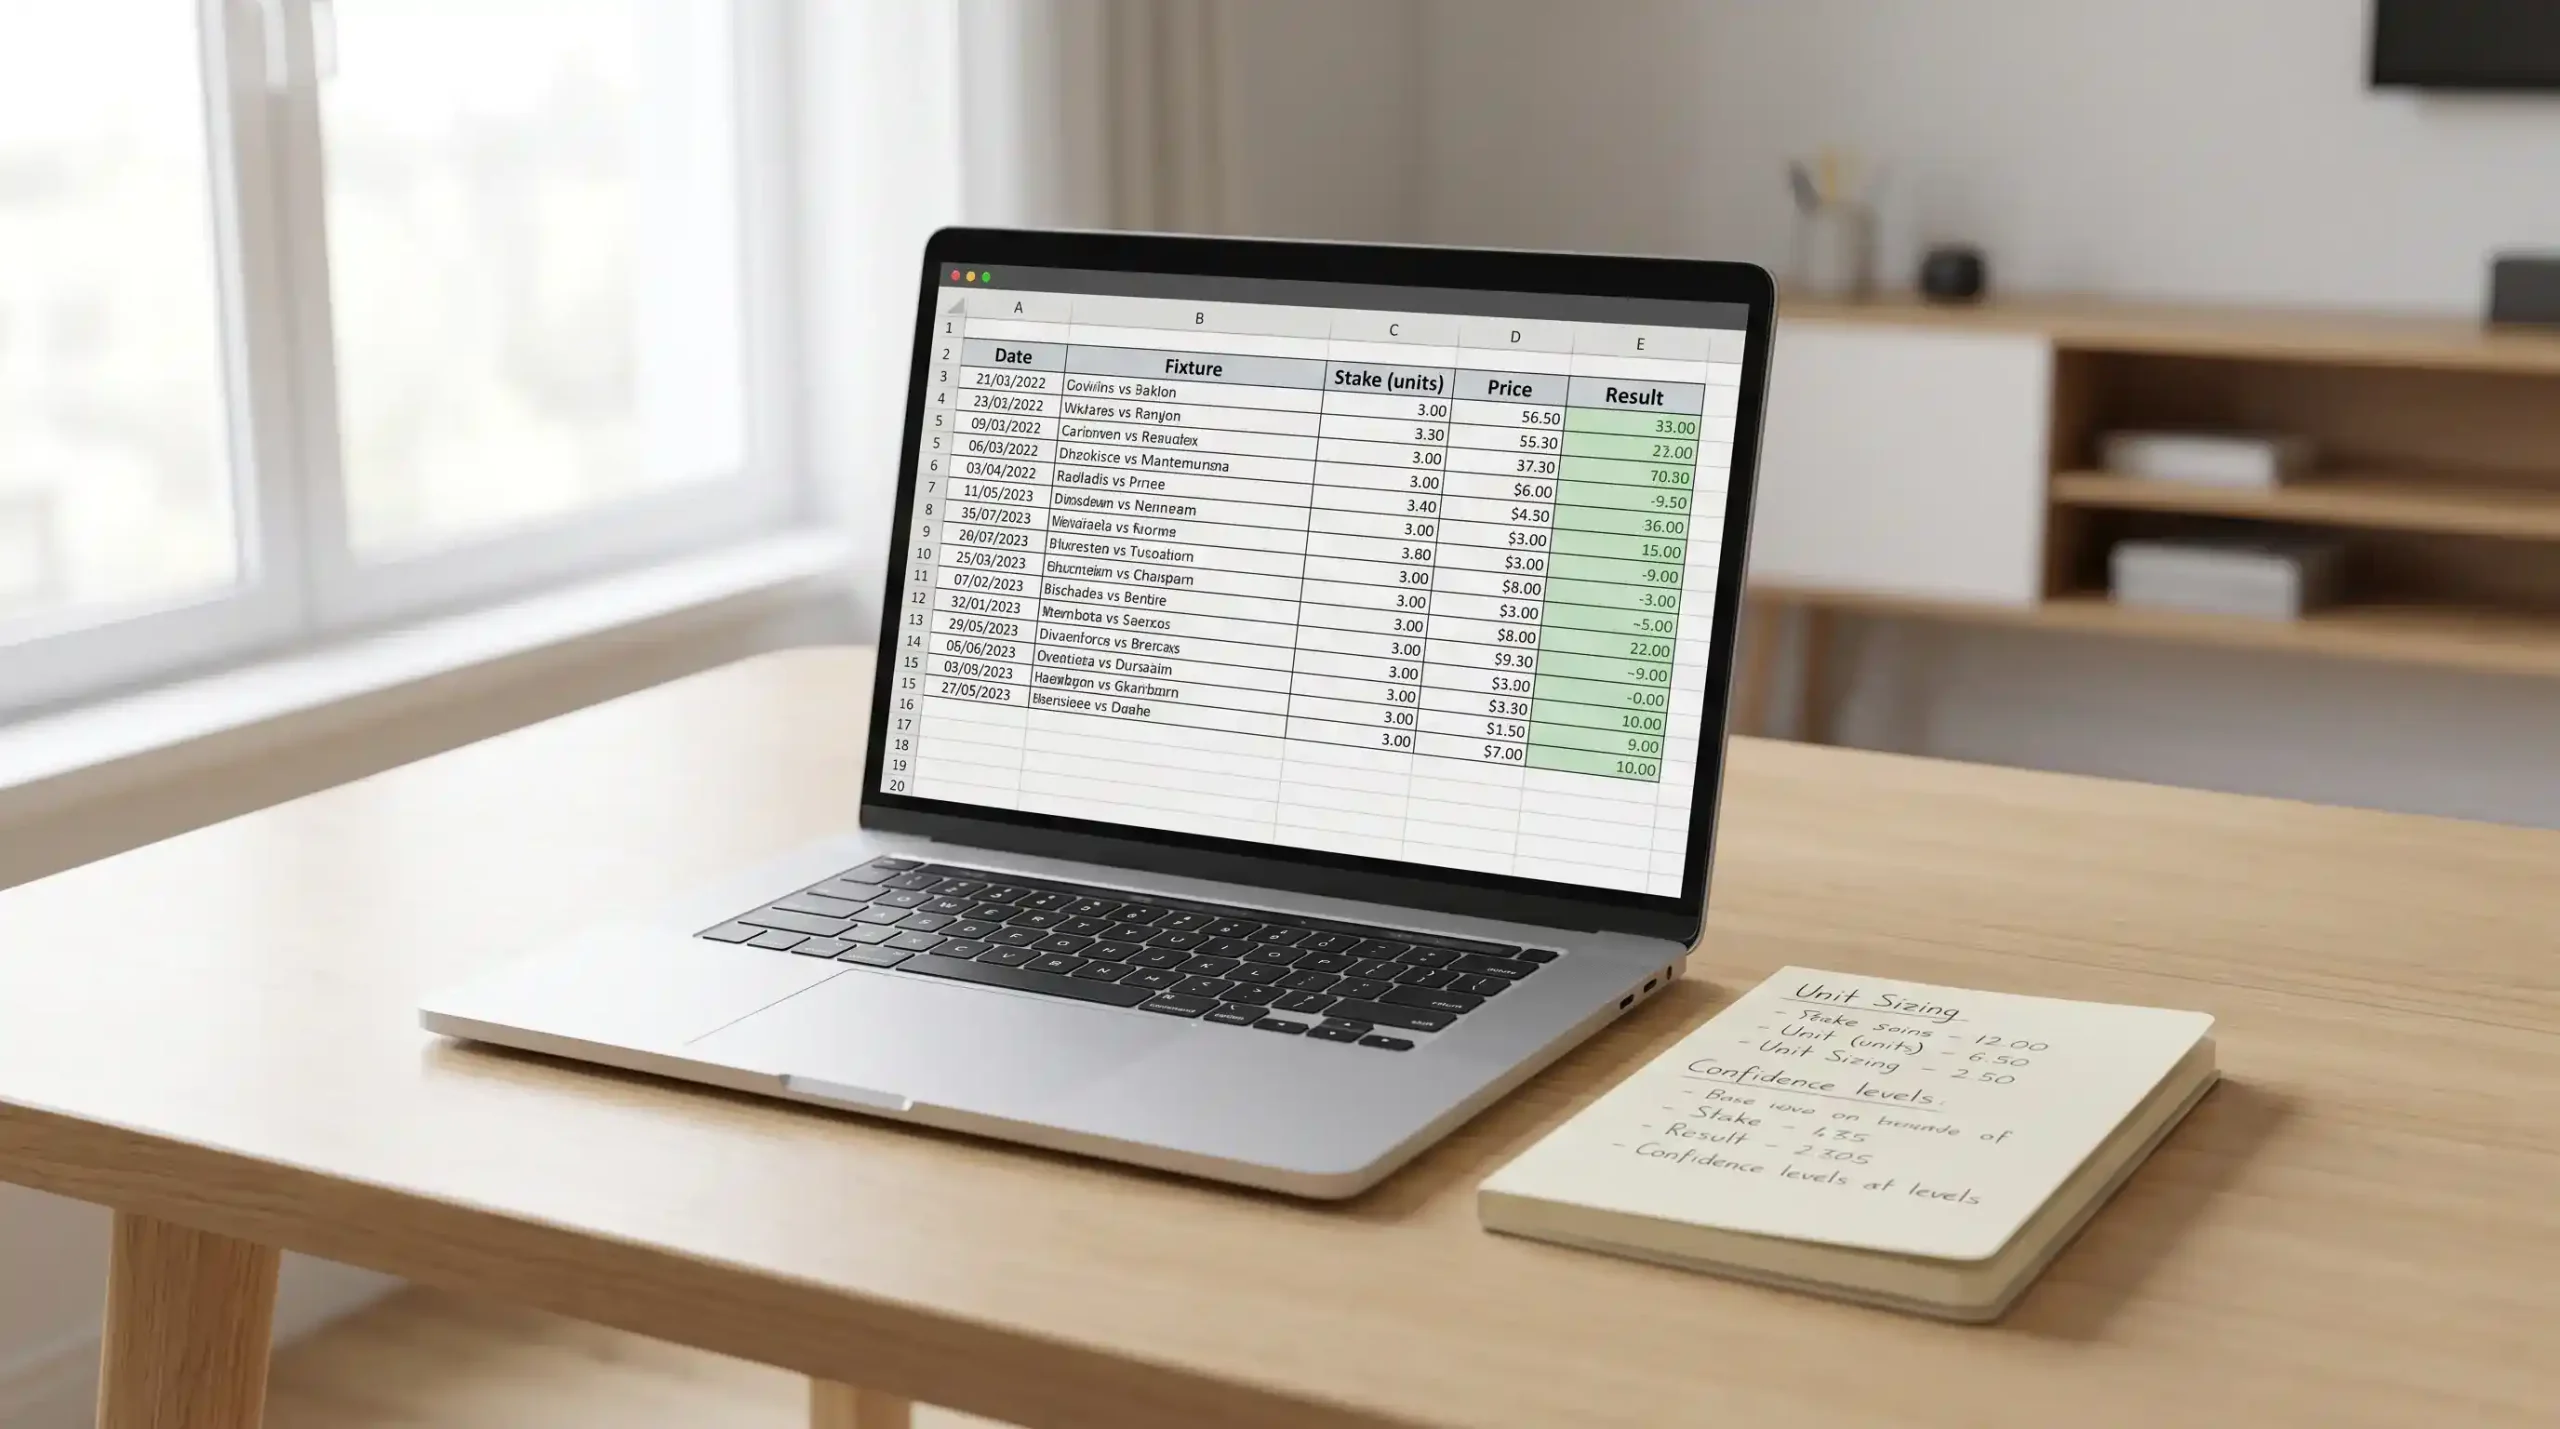
Most professional bettors track stakes in “units” rather than pounds. A unit is typically 1-2% of bankroll, fixed for a season or until significant bankroll growth justifies adjustment. Bets are then sized at 1u, 2u, or occasionally 3u based on edge confidence.
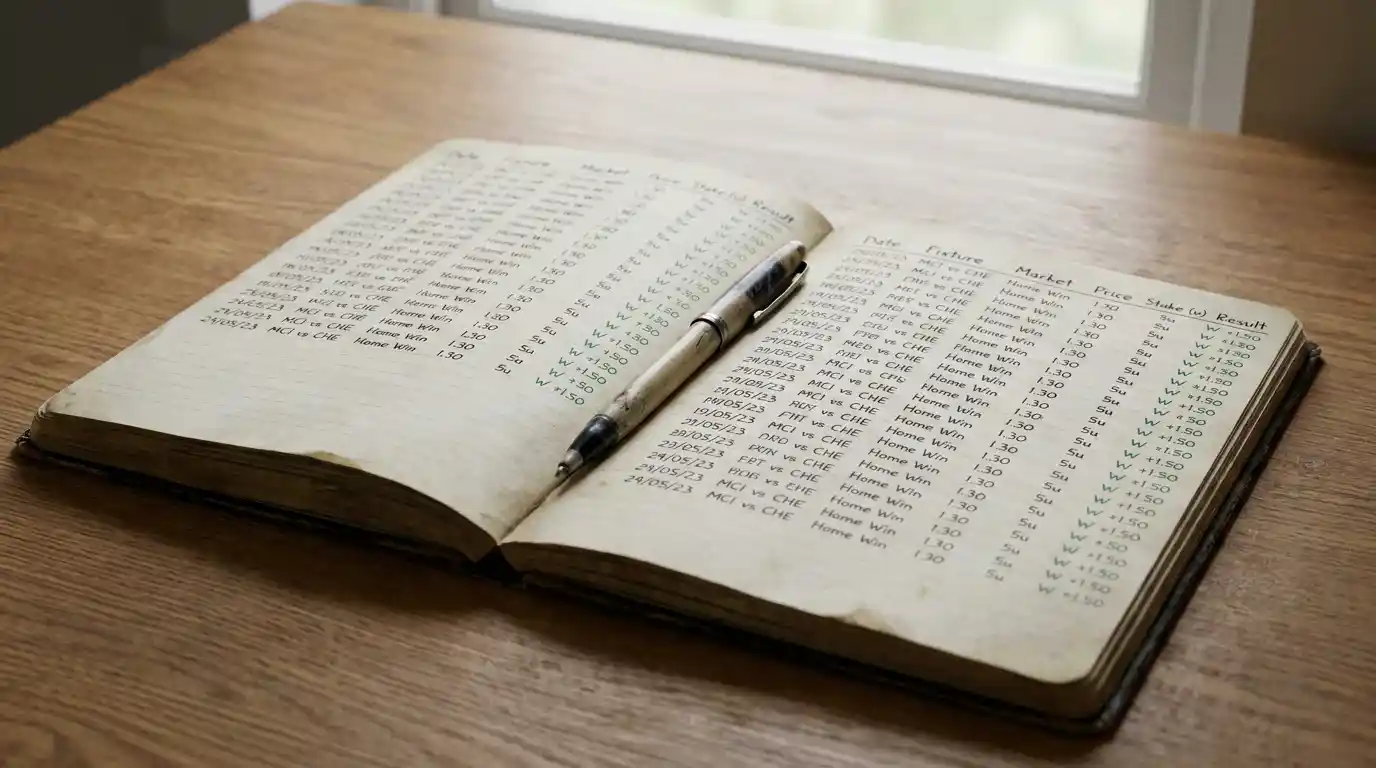
The unit system has three structural benefits. First, it depersonalises the stake — you’re betting 2u, not “£50 of my actual money”, which reduces emotional weight. Second, it scales automatically as the bankroll grows or shrinks — if your bankroll halves, your unit halves with it, keeping the percentage exposure consistent. Third, it forces explicit confidence calibration on every bet — you can’t bet 2u without committing to the view that this specific bet is higher confidence than your 1u baseline.
The unit system pairs with disciplined record-keeping. Every bet recorded with date, fixture, market, price, stake (in units), result, and ideally closing line value. Without records, learning from your own betting history is impossible. With records, your patterns become visible — which markets you bet well in, which leagues you should avoid, which days of the week your selection quality dips.
The variance reality check
Run a simple simulation: 100 bets at 3.00 with 35% true probability. Expected return is +5%. Expected outcome is winning 35 of 100. Now ask what range the actual outcome will fall in 95% of the time. The answer: between 26 and 44 wins. That’s a 70% swing in realised outcomes against the same true edge.
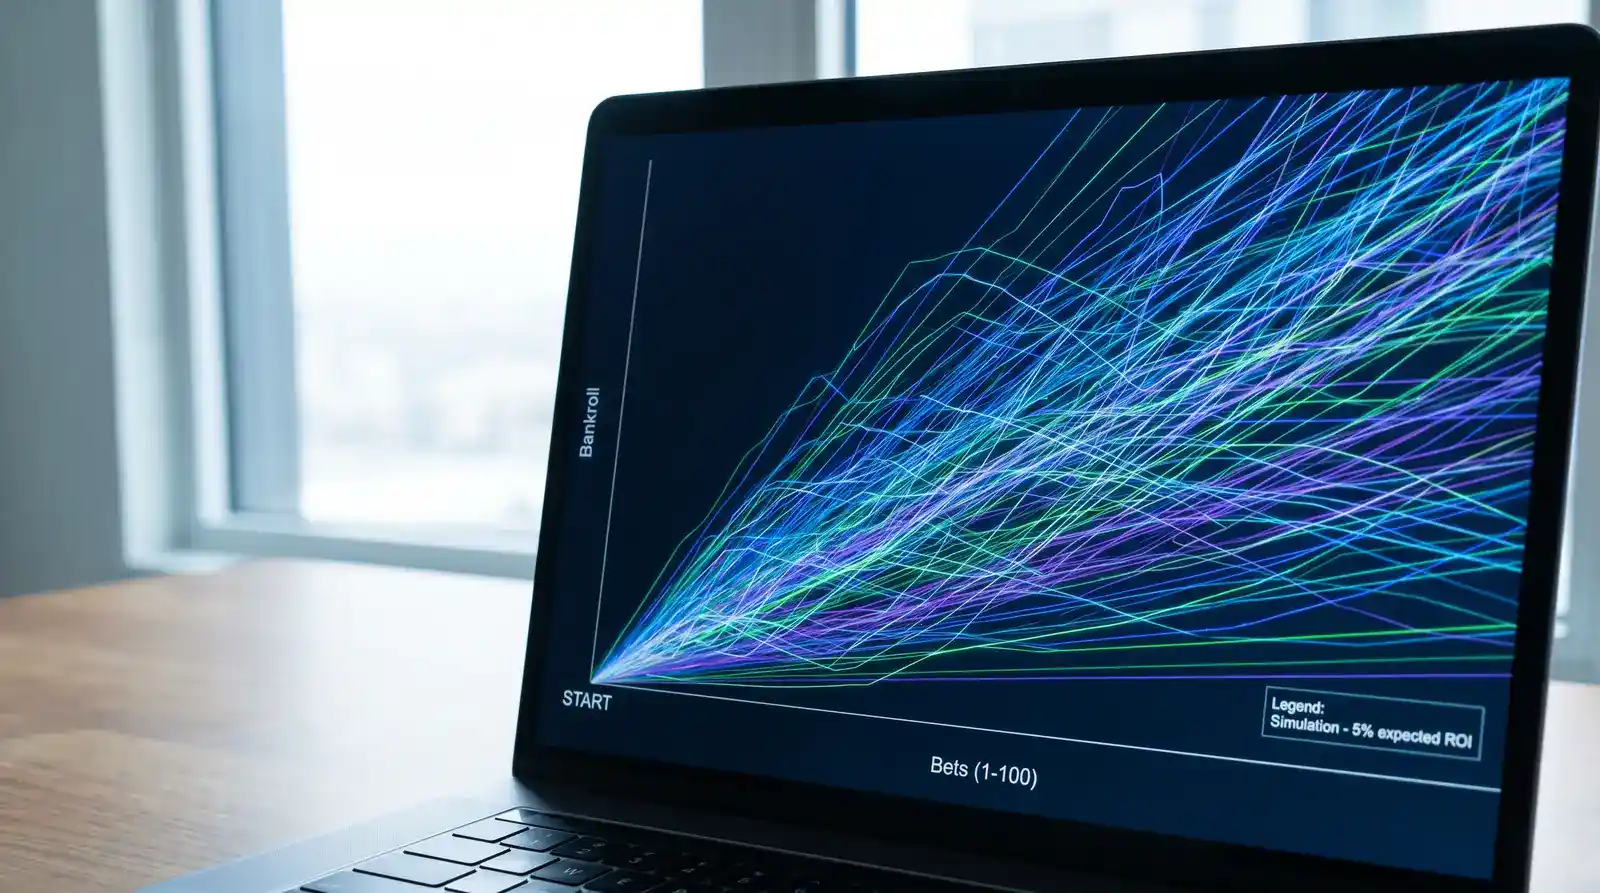
Translate that into bankroll terms. A 100-bet sample at 2% stake-per-bet sees realised ROI range from −22% to +32% in 95% of simulation runs. The same underlying edge can produce a fifth-down bankroll or a third-up bankroll purely from variance. The value-betting framework only delivers its expected long-run results across thousands of bets, not hundreds.
That reality is why bankroll management has to assume the worst likely variance event will happen, not the average expected outcome. A bankroll sized for the average outcome blows up in the bottom-5% scenarios. A bankroll sized for the bottom-5% scenario sustains through them.
Stop-loss disciplines and when to walk away
Some punters use stop-loss rules — “if I’m down 40% from peak, I stop betting for a month and review the strategy”. The rule is defensible if the review actually identifies a process error. It’s destructive if it leads to abandoning a sound strategy mid-variance event.
The better discipline is process review at regular intervals — every 100 bets, regardless of result. Check CLV. Check whether the markets you’re betting are the markets where your edge is highest. Check whether your stake sizing matches your stated rules. The review at fixed intervals catches genuine process drift; the stop-loss at variance thresholds usually catches normal variance and mis-identifies it as process failure.
That’s also why the regulatory framework around responsible play matters at the bankroll level. The Gambling Commission’s tools — deposit limits, time-outs, self-exclusion — operate at the financial commitment layer, not the strategy layer. They’re designed to catch the bankroll-management failure modes that most often correlate with harm. Setting a deposit limit at 2x your monthly betting budget creates external friction against the “doubling up to win back losses” pattern that destroys most retail bankrolls.
Account distribution and operator-side variance
Distributing bankroll across multiple UK operators is operationally useful but not strategically critical for most punters. The case for multiple accounts: price-shopping for individual selections, capturing promotional offers across operators, hedging against operator-side issues like restricted accounts.
The case against: increased account-management overhead, verification friction at each operator, deposit caps split across accounts. UK gambling reported 34M new registrations across the licensed market last year — and a non-trivial share of those registrations were single-purpose bonus claims that never developed into ongoing betting relationships. For the value-focused bettor, two or three primary accounts plus an exchange account is usually optimal.
The other dimension is account longevity. Operators that restrict winning customers — common across UK sportsbooks once consistent profit appears — force the value punter into exchange-only betting eventually. Maintaining accounts with operators that don’t impose restrictions is a real consideration in the multi-account strategy, even if those operators have wider overrounds. The exchange becomes the venue for placing bets that have been priced out of sportsbook routes.
The compounding question
Reinvesting profits — letting the bankroll grow and scaling stakes proportionally — is the standard approach for serious value bettors. The mathematics favours compounding: a 5% ROI grown over 100 bets per month produces faster bankroll growth at proportional stake sizing than at flat stake sizing.
The behavioural question is when to withdraw versus when to reinvest. Most disciplined punters set a target bankroll size, withdraw profits beyond that target, and reset the unit size periodically as the bankroll grows. That structure converts the betting strategy into a steady income stream rather than an unbounded growth experiment, and it locks in profits against future variance events.
The opposite pattern — never withdrawing, letting the bankroll compound indefinitely — works mathematically but exposes the entire accumulated bankroll to future variance. A two-year compounded bankroll that has tripled in size still has a 5% probability of substantial drawdown in any given month. Withdrawing some portion of the growth creates resilience against that drawdown.
What separates the disciplined punter from the rest
Three habits. First, consistent stake sizing aligned to an explicit rule — units of bankroll, not “what feels right today”. Second, disciplined record-keeping that lets the punter learn from their own history. Third, willingness to ride out normal variance without changing the strategy mid-drawdown.
None of those habits is hard individually. Together, they’re rare. Most retail punters bet larger when winning, smaller when losing, in markets they don’t understand at prices they didn’t shop for. That pattern produces faster losses than the underlying selection quality would predict. The disciplined punter does the opposite — consistent stakes, in shopped-for prices, in markets they understand, regardless of recent results.
Bankroll management is the unsexy half of football betting, and it’s the half that determines whether all the other analytical work pays off or not. The selection edge matters. The bankroll management is what lets the selection edge eventually realise itself as profit rather than evaporating into variance.
Start with flat stakes at 1-2% of bankroll per wager. A £1,000 bankroll bets £10-20 per selection regardless of confidence level. This removes stake sizing as a variable while you focus on building selection skills. Move to proportional staking only after you"ve built a CLV record across 200+ bets demonstrating actual edge. At least 100 average bet sizes. If you want to bet £20 per selection, you need a £2,000 bankroll. Anything less and your strategy can"t survive a normal losing streak. Most retail bankroll failures come from being under-capitalised — betting 5-10% per wager when sustainable sizing is 1-2%. Set a target bankroll size and withdraw growth beyond it. A £2,000 starting bankroll that reaches £3,000 might withdraw £500 to lock in profit and reset the unit size against the £2,500 remainder. Letting bankrolls compound indefinitely exposes accumulated growth to future variance — taking partial withdrawals creates resilience against drawdown events that will eventually happen.What stake size should I use as a beginner?
How much bankroll do I need to start betting football seriously?
When should I withdraw profits rather than reinvest?
This material was created by the Pitchledger team.
